
Key takeaways
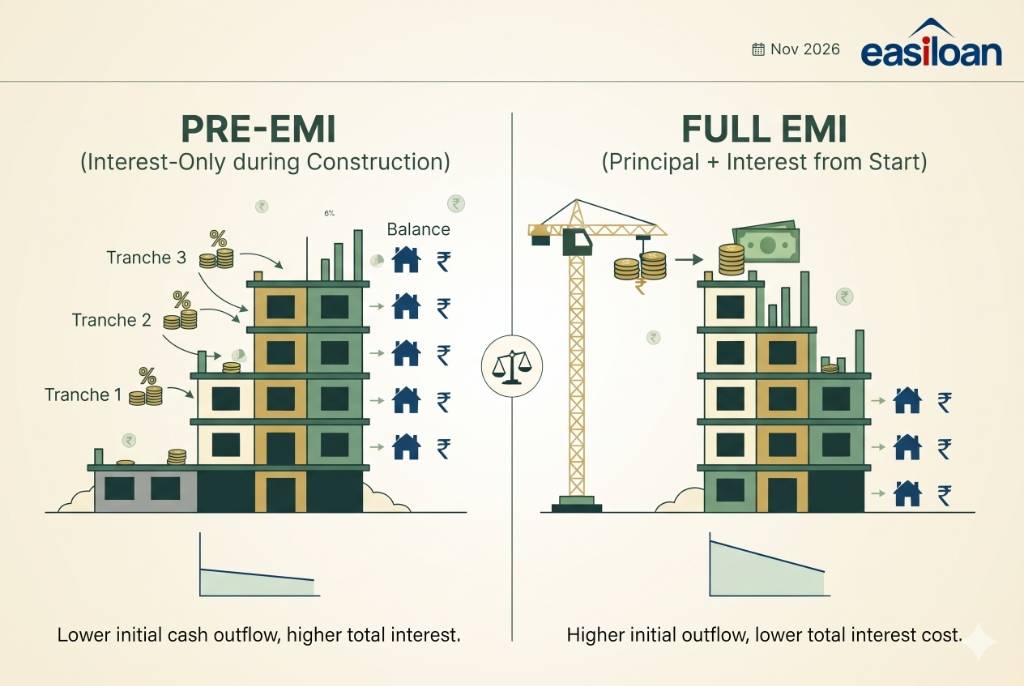
- Pre-EMI means paying only interest on the amount disbursed so far; full EMI means paying principal plus interest from the first disbursal.
- Pre-EMI keeps early outgo low but the principal does not fall, so total interest over the life of the loan is higher.
- Illustrative: on a ₹60 lakh sanction at 8.75%, pre-EMI climbs from about ₹8,750 to ₹43,750 a month as disbursals accumulate, before the full EMI of ₹53,023 starts.
- Plan for both rent and pre-EMI overlapping while you wait for possession.
Why this choice exists
When you buy an under-construction property, the lender does not hand over the whole sanctioned amount on day one. It releases money in stages linked to construction progress, as we explain in our guide to sanctioned vs disbursed amounts. Each tranche starts accruing interest. You then choose how to service that interest and principal while waiting for possession.
Option 1: Pre-EMI (interest only)
You pay interest on the disbursed amount only. The principal stays untouched until the regular EMI begins, usually after the final disbursal or possession.
- Pros: lower outgo in the early years, useful if you are also paying rent.
- Cons: no reduction in principal, so total interest cost is higher, and a delayed project extends the period.
Option 2: Full EMI from the first disbursal
You pay principal and interest on whatever has been disbursed. As more is released, the EMI is recalculated or the tenure adjusts.
- Pros: principal reduces from the beginning, saving interest over time.
- Cons: higher monthly outgo while you may still be paying rent.
An illustrative stage-wise schedule
Assume a ₹60 lakh sanction at 8.75%, disbursed in four stages tied to construction milestones. The pre-EMI column shows monthly interest on the cumulative disbursed amount.
| Stage | Tranche | Cumulative disbursed | Monthly pre-EMI |
|---|---|---|---|
| Foundation / plinth | ₹12,00,000 | ₹12,00,000 | ₹8,750 |
| Structure (slabs) | ₹18,00,000 | ₹30,00,000 | ₹21,875 |
| Brickwork & plaster | ₹18,00,000 | ₹48,00,000 | ₹35,000 |
| Possession | ₹12,00,000 | ₹60,00,000 | ₹43,750 |
Once the full amount is out, a 20-year EMI is about ₹53,023. This is a simplified model; real schedules follow your builder's milestones and your lender's policy.
Budget tip: stack three costs when planning: current rent, pre-EMI, and the savings you still need for registration and interiors. Many buyers underestimate the overlap period.
How to choose
| If you… | Lean towards |
|---|---|
| Pay significant rent now and have tight cash flow | Pre-EMI |
| Have strong surplus and a long delivery timeline | Full EMI |
| Expect income growth soon | Pre-EMI, then plan part-prepayments |
| Are buying a project with a poor delivery record | Be conservative and verify the project first |
Questions to ask the lender and builder
- When does the full EMI start: on final disbursal or on possession?
- Is the pre-EMI option available, and can I switch later?
- Do disbursals match RERA-registered construction stages?
- What happens to my interest if possession is delayed?
Start with RERA verification so that your timeline rests on a project that is properly registered.
Frequently asked questions
What is pre-EMI?▾
Pre-EMI is the interest-only payment on the portion of the loan disbursed so far. It applies while a property is under construction and disbursals happen in stages.
What is full EMI during construction?▾
You start paying the regular EMI, which includes principal and interest, from the first disbursal. The EMI rises as each tranche is released, or the tenure is adjusted by the lender.
Which option is cheaper overall?▾
Full EMI from the start generally reduces total interest because principal starts falling earlier. Pre-EMI preserves cash early on, so the better choice depends on your budget.
Can I switch from pre-EMI to full EMI?▾
Many lenders allow it on request, sometimes with a fee. Ask for the rule before accepting the sanction.
How is pre-EMI interest treated for tax?▾
Interest paid before possession is generally claimed in instalments after possession rather than year by year. Rules and caps differ by regime, so confirm with a tax professional.
Keep reading
This article is for general information and is lender-neutral. Interest rates, fees and policies change and vary by lender and borrower profile; figures marked illustrative are examples, not offers. Tax and legal points are not professional advice, so please confirm with a qualified professional. Credit is at the sole discretion of the lender, subject to appraisal, eligibility, rates, charges and terms.